Evaluating the best flood insurance policies for homeowners in flood zones
A comprehensive guide to evaluating and selecting the best flood insurance policies for homeowners in high-risk zones, comparing NFIP and private options.
Introduction to flood risks and insurance realities
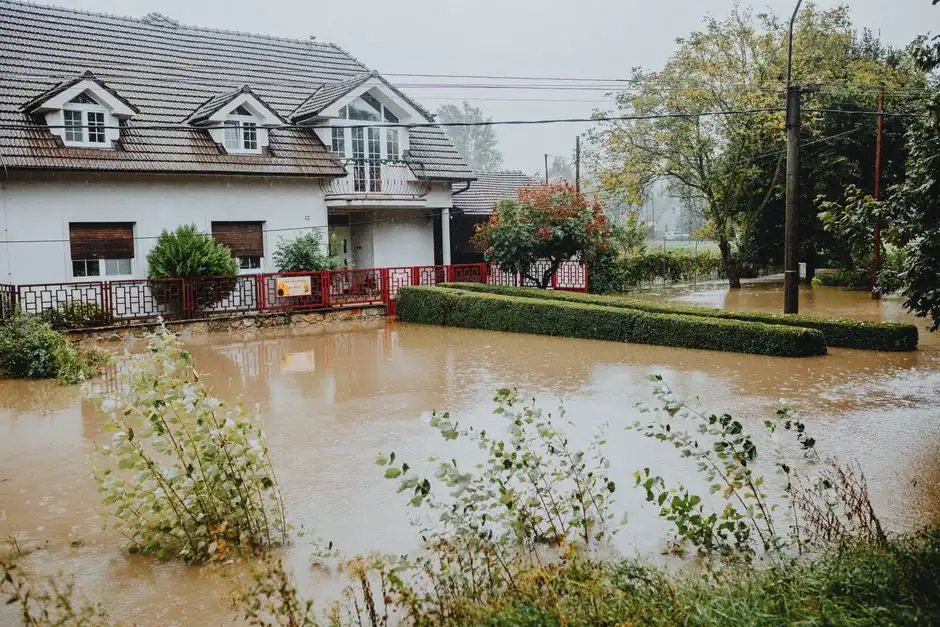
Flooding is the most frequent and financially damaging natural disaster in the United States. Between 2014 and 2023, damage from flooding cost an average of $46 billion a year to repair, according to the Congressional Budget Office. With the impact of climate change, that financial burden is projected to increase by at least a quarter in the next 25 years. Despite these statistics, close to a quarter of homeowners in designated flood zones still do not carry active flood insurance.
Many property owners mistakenly believe that standard homeowners insurance—a key component of choosing the right personal insurance—covers flood damage. In reality, standard policies explicitly exclude floods; homeowners must secure a standalone flood insurance policy to protect both their dwelling and personal belongings. Those who miss this distinction often discover their vulnerability only after a severe storm or overflowing body of water has inundated their property. Over a standard 30-year mortgage, homes in Federal Emergency Management Agency high-risk flood zones are statistically more likely to experience flood damage than a fire.
Coverage typically falls into two categories: federal programs and private insurance markets. While the National Flood Insurance Program has historically been the default choice for millions of Americans, private insurers now offer alternatives with higher limits, broader protection, and fewer exclusions. Homeowners must weigh factors such as mortgage lender requirements, coverage limits, deductibles, waiting periods, and unique property characteristics when choosing the best flood insurance before committing to a policy.
Navigating FEMA flood zones and risk levels
26%+
Minimum flood probability over a 30-year mortgage in SFHAs
3+ ft
Breaking wave height threshold for coastal V/VE zones
$25,000
Potential structural and contents damage from a single inch of water
Source: FEMA
Understanding flood risk begins with examining FEMA flood maps, which categorize land by risk level using specific lettered zones. The highest risk areas are officially designated as Special Flood Hazard Areas, encompassing zones labeled A, AE, V, and VE. In FEMA terminology, SFHAs carry a 1% or greater chance of flooding in any given year, commonly referred to as the 100-year floodplain. Over a 30-year mortgage, that annual probability compounds to a 26% chance or higher of experiencing a flood event, which is more likely than the statistical risk of a domestic fire.
Zone AE is a common coastal or inland flood zone with a well-defined base flood elevation, making it heavily regulated for insurance and building requirements. Zones V and VE apply to coastal areas facing severe additional hazards from storm wave action—which is why it's vital to know how to prepare your home for a coastal flood advisory—where breaking wave heights of 3 feet or greater can uproot foundations and move debris into structures. Meanwhile, Zone A typically applies to inland areas featuring floodplains without detailed elevation studies. Flood maps are not always up to date; urban development, aging stormwater management systems, and changing weather patterns mean neighborhoods outside official high-risk zones can still experience severe flooding.
Mandatory purchase requirements apply to properties situated in high-risk FEMA flood zones if the owner holds a federally backed mortgage. Mortgage lenders actively enforce this rule, requiring proof of flood insurance prior to closing a real estate transaction. If a homeowner allows this coverage to lapse, the lender maintains the legal right to force-place insurance on their behalf. Force-placed policies are often expensive and generally provide inferior coverage compared to policies a homeowner selects independently. Even homeowners who own their properties outright should consider flood insurance an important investment, given that a single inch of water can cause up to $25,000 in structural and property damage.
Comparing National Flood Insurance Program and private policies
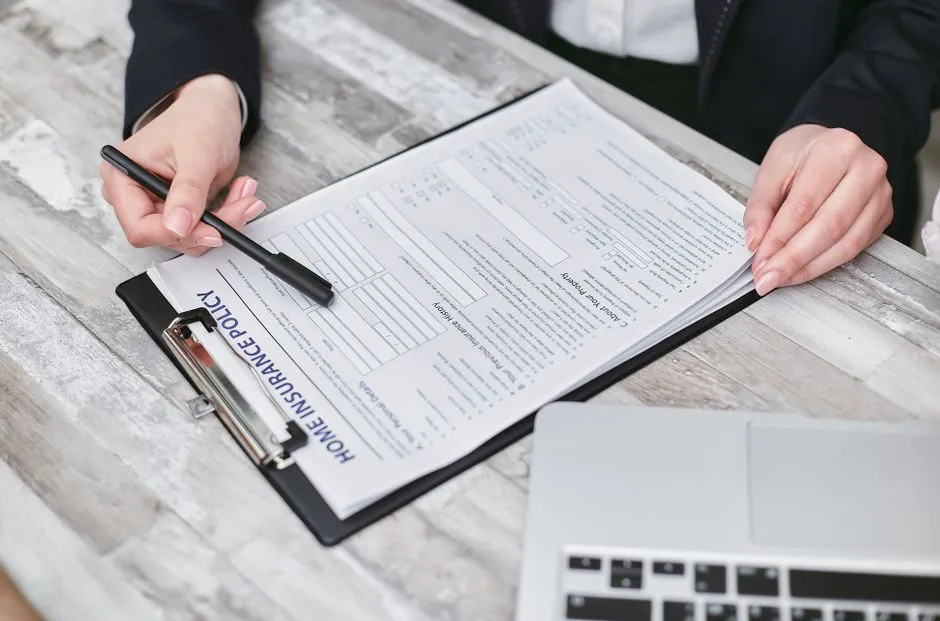
When shopping for coverage, homeowners should evaluate whether a federal policy through the National Flood Insurance Program or a private insurance policy best fits their needs. The NFIP is administered by FEMA and partnered with dozens of insurance carriers, meaning all NFIP policies offer identical coverage terms and federally regulated rates regardless of which company sells them. NFIP policies are accessible to anyone in a participating community, providing a baseline of protection for standard residential properties.
However, NFIP policies have strict statutory coverage caps. The maximum dwelling coverage available through the NFIP is $250,000, with a $100,000 limit for personal contents. For high-value homes or properties with significant renovations, these caps are often insufficient to cover total reconstruction costs. Furthermore, the standard NFIP policy excludes several major expense categories, including additional living expenses like temporary hotel stays, damage to outdoor property such as fences and pools, basement improvements like finished drywall and carpeting, and vehicle damage.
Private flood insurance companies fill these gaps by offering policies with higher limits, customized endorsements, and broader definitions of coverage. Private insurers frequently provide dwelling limits extending into the millions, personal property coverage tailored to luxury items, and loss of use protection to cover temporary housing costs. Additionally, private carriers often use advanced data modeling to price premiums based on exact property elevation and risk data rather than broad zone classifications.
Evaluating top private and federal flood insurance providers
Comparison of Featured Flood Insurance Providers
| Provider | Coverage Type / Limits | Notable Features | Waiting Period |
|---|---|---|---|
| Aon Edge | Private (Up to $1.25M dwelling / $875K contents) | Premiums avg. 40% below NFIP; four deductible tiers ($1K–$10K) | Standard private wait |
| Neptune Flood | Private (Limits reaching several million dollars) | Pool and enclosure coverage; tailored high-risk protection | As brief as 10 days |
| Amica | NFIP Partner (Standard federal caps) | Bundling options with auto, life, and umbrella policies | 30 days (standard NFIP) |
| Kin | Private Endorsement (FL & LA) | Single deductible combined with standard homeowners policy | Immediate binding in FL |
The flood insurance marketplace features several providers catering to different homeowner priorities, ranging from low rates and high-value home protection to specialized regional coverage. Aon Edge is a strong option for homeowners seeking low rates, as noted in a review of the best flood insurance companies, with average premiums running approximately 40% below typical NFIP policies. Aon Edge offers flexible plans such as the EZ Flood plan, which provides up to $1.25 million in building coverage and $875,000 in contents coverage, alongside four distinct deductible tiers ranging from $1,000 to $10,000 without requiring an elevation certificate in many cases.
For homeowners requiring specialized protections, companies like Neptune Flood have expanded the market by offering private coverage for high-risk flood zones, including specialized pool and enclosure coverage, short waiting periods as brief as 10 days, and maximum coverage limits reaching up to several million dollars for high-risk properties. Beyond specialized private carriers, traditional insurers participating in the NFIP, such as Amica, are known for their customer service and bundling discounts. Amica allows policyholders to combine their flood insurance with auto, life, or umbrella policies, though policyholders must pay their annual premiums in a single lump sum and contact customer service directly for rate quotes.
Regional private insurers also serve specialized markets. For instance, Kin provides flood insurance as an add-on endorsement to homeowners policies in select disaster-prone states like Florida and Louisiana. This integration allows Florida homeowners to purchase flood insurance alongside their standard property coverage under a single deductible, eliminating the standard waiting period entirely within the state. When evaluating these providers, homeowners should review waiting periods, which range from immediate binding for certain private endorsements to the mandatory 30-day waiting period enforced by standard NFIP policies.
Key factors in selecting the right coverage amount
Coverage Evaluation Checklist
- Calculate true structural rebuilding costs — Base coverage limits on local construction prices rather than market value or mortgage balances.
- Opt for replacement cost value on contents — Protect personal belongings against actual cash value depreciation deductions.
- Review structural and contents deductibles separately — Account for cumulative out-of-pocket costs across both coverage categories during a claim.
- Identify exclusions and secure excess coverage — Address gaps in living expenses or finished basements with private excess riders.
Determining the correct amount of flood insurance requires a careful assessment of both structural replacement costs and personal property inventory. Homeowners must calculate the true cost of rebuilding their home from the foundation up at current local construction and material prices, ensuring their dwelling coverage limit matches or exceeds this figure. Relying solely on real estate market value or mortgage loan balances can leave a property underinsured, as land value does not factor into structural rebuilding costs.
Personal property coverage, often referred to as contents insurance, must account for the actual replacement cost value of furniture, electronics, clothing, appliances, and stored belongings. While basic policies may default to actual cash value, which depreciates the payout based on the item's age and condition, replacement cost value policies ensure the homeowner receives sufficient funds to purchase brand-new equivalent items. Homeowners should also review policy deductibles, keeping in mind that flood insurance policies often feature separate, cumulative deductibles for the structural building and personal contents, meaning out-of-pocket expenses can accumulate during a claim.
Finally, policyholders should review potential policy exclusions and secure supplemental coverage where gaps exist. If a standard NFIP policy leaves out living expenses or basement finishes, purchasing excess flood insurance or a specialized private policy can fill those gaps. Consulting with an insurance agent to find a reliable agency and utilizing a homeowner’s guide to flood-proofing ensures that homeowners set up a comprehensive protection plan before the next major storm season arrives.
References
Keeping pets safe and stress-free during natural weather emergencies
How to prepare your home for a coastal flood advisory
Related Posts
LIFEKeeping pets safe and stress-free during natural weather emergencies
A comprehensive guide on how to prepare emergency kits, establish evacuation plans, and minimize anxiety for pets during natural disasters.
LIFEHow to prepare your home for a coastal flood advisory
Learn how to protect your home and property when the National Weather Service issues a coastal flood advisory with this practical, step-by-step preparation guide.